‘ନିଓକ୍ଲାଉଡ୍ ଫାଇନାନ୍ସିଂ’ (Neocloud Financing) ବୁଝାମଣା: AI ଡାଟା ସେଣ୍ଟର ପାଇଁ ୪୦ ବିଲିୟନ ଡଲାର ଯୋଗାଡ଼ କରିବାକୁ ନେବିୟସ୍ (Nebius) ର ଯୋଜନା
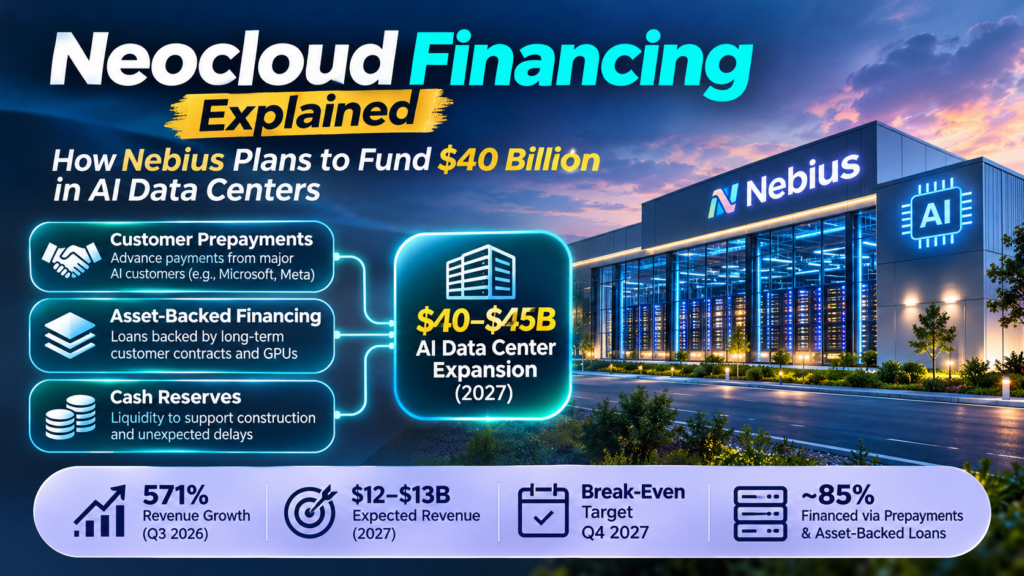
Neocloud financing is the practice of paying for GPU data centers with money that customers and lenders commit before the capacity exists, and Nebius is now betting roughly $40 billion to $45 billion of 2027 spending on it. The approach works beautifully when sites are delivered on schedule, and it gets expensive fast when they are not, which is exactly the tension Nebius exposed on its November 12, 2026 earnings call.
If you follow AI infrastructure, this is one of the most important stories of the quarter. Nebius posted explosive growth, then lost 17% of its share price in a day because the way it pays for that growth is being stress-tested in public. This guide explains what happened, how the money is supposed to flow, and what could break it.
Key Takeaways
- Nebius laid out about $40 billion to $45 billion in 2027 capital spending, far more than Wall Street expected, according to TechCrunch and Reuters reporting.
- The company expects customer prepayments plus asset-backed loans to cover up to 85% of that bill.
- A Microsoft-funded site in Vineland, New Jersey is months behind schedule, and only just over half of that capacity is planned for delivery by the end of 2026.
- Nebius cut its 2026 revenue forecast by $200 million to $3 billion and still reported third-quarter revenue of $981 million, up 571% year over year.
- Neocloud financing is a leveraged bet on execution: delays raise costs and push revenue out at the same time.
What Is Neocloud Financing?
Neocloud financing is the set of funding methods that GPU-focused cloud providers use to build data centers: customer prepayments, loans secured by signed customer contracts, equity, and cash on hand. It exists because building AI capacity costs billions up front, while the revenue arrives slowly over multi-year contracts.
In other words, a neocloud sells future computing capacity and then uses the promise of that sale to raise the money needed to build it. The lender or customer is effectively underwriting a contract, not a track record of profits.
What Is a Neocloud?
A neocloud is a cloud provider built around renting GPU computing power for AI workloads rather than offering a broad menu of software services. Research firm SemiAnalysis, which popularized the term in its “AI Neocloud Playbook,” describes the category as a new breed of provider focused on GPU compute rental. Synergy Research Group estimated that the sector generated more than $25 billion in revenue in 2025.
Nebius is one of the best-known examples. It is Amsterdam-based, spun out of Yandex’s international operations, and counts Microsoft and Meta among its largest customers.
How Is Neocloud Financing Different From Hyperscaler Funding?
Hyperscalers such as Microsoft, Amazon, and Google pay for data centers largely from enormous operating cash flows. Neoclouds do not have that cushion, so neocloud financing leans on outside capital that is tied to specific contracts. That structure is cheaper and faster than raising generic equity, but it ties the company’s financial health to project timelines.
| Feature | Hyperscaler funding | Neocloud financing |
|---|---|---|
| Main source of capital | Operating cash flow from large existing businesses | Customer prepayments, contract-backed loans, equity |
| Dependence on a few customers | Low | High |
| Sensitivity to construction delays | Moderate | High |
| Revenue diversification | Broad software and cloud portfolio | Concentrated in GPU capacity |
| Speed of scaling | Limited by internal planning | Limited by financing and power availability |
What Did Nebius Announce on November 12, 2026?
Nebius used its third-quarter earnings call to present a 2027 plan of $40 billion to $45 billion in capital expenditures, alongside forecast 2027 revenue of $12 billion to $13 billion and an expectation of pre-tax break-even by the fourth quarter. Reuters, as summarized by Digg, also reported that 2026 spending was raised to about $27 billion from a prior range of $20 billion to $25 billion.
The headline Nebius capex number is large because demand from AI customers is large, but it also reflects a bet that the company can keep finding partners willing to pay in advance.
The Numbers at a Glance
| Metric | Figure reported |
|---|---|
| 2027 capital expenditure plan | $40 billion to $45 billion |
| 2027 revenue forecast | $12 billion to $13 billion |
| Share of 2027 capex covered by prepayments and asset-backed financing | Up to 85% |
| Q3 2026 revenue | $981 million (up 571% year over year) |
| Cash at quarter end | $7.4 billion |
| Revised 2026 revenue forecast | $3 billion (cut by $200 million) |
| Microsoft contract value | Up to $19.4 billion |
| Share price reaction | Down 17% on the day |
A note on that revenue figure: roughly a third of third-quarter revenue was a one-time payment tied to a new partnership model, so the underlying run rate is lower than the headline growth rate suggests.
Why Did Nebius Shares Fall 17%?
Investors reacted to the combination of a lowered 2026 revenue forecast and a much bigger spending plan. Reuters reported that delayed capacity pushed some expected sales into 2027, and that Nebius now expects to reach its $7 billion annual run-rate revenue target roughly two months later than planned. When spending accelerates while revenue slips, markets start asking how the gap will be funded.
How Does Nebius Plan to Pay for $40 to $45 Billion in Spending?
Nebius plans to pay for the build-out mainly through customer prepayments and asset-backed financing, with cash on hand as a backstop. Management said these two sources together are expected to cover up to 85% of the 2027 capital budget. Reuters reported the range as 75% to 85%.
Here is how each piece works.
Customer Prepayments
Customer prepayments are cash payments that customers make before the capacity they bought is delivered. Nebius chief revenue officer Marc Boroditsky said the Microsoft and Meta deals both carried significant prepayments that arrived long before delivery, and that new deals signed in the third quarter came with prepayments that more than cover the cost of the capacity behind them.
For the customer, prepaying can secure scarce GPU supply. For Nebius, the cash reduces how much it must borrow. The catch is that a prepayment is, in effect, a promise to deliver. If a site slips badly enough, the customer may have contractual rights to penalties or termination.
Asset-Backed Financing
Asset-backed financing is borrowing that is secured by specific assets, in this case data center equipment and, more importantly, the stream of payments from signed customer contracts. Nebius CFO Maria Del Dado Alonso Sanchez named the Microsoft and Meta agreements as contracts that can be financed this way, and the company says it can finance investment-grade contracts using this method.
Lenders like this structure because the borrower’s repayment is linked to a large, creditworthy customer rather than to the neocloud’s general profitability. The downside is that if the underlying contract is renegotiated or delayed, the collateral gets weaker.
Cash on Hand
Nebius ended the quarter with $7.4 billion in cash. That is meaningful, but it is small next to a $40 billion-plus annual plan, which is why the company also said it could tap prepayments to shore up any additional cash needs.
Neocloud Financing Sources Compared
Different funding sources carry different costs and risks. The table below is an analytical comparison, not a statement of Nebius’s own terms.
| Funding source | Speed | Dilution to shareholders | Main risk |
|---|---|---|---|
| Customer prepayments | Fast, tied to contract signing | None | Delivery penalties or termination if capacity is late |
| Asset-backed financing | Moderate, requires signed contracts | None | Collateral weakens if contracts change |
| Equity issuance | Fast when markets are open | Yes | Falling share price makes it costlier |
| Unsecured debt | Depends on credit markets | None | Harder to get without independent revenue |
The pattern is clear: the cheapest sources of money in neocloud financing are also the ones most sensitive to delivery performance.
What Is the Neocloud Playbook?
The neocloud playbook is a repeatable growth strategy: sign long-term contracts with large AI customers, use those contracts to raise prepayments and secured debt, build the data centers, then deliver capacity and recognize revenue. TechCrunch framed Nebius’s plan as a test of this playbook because every step depends on the previous one working on time.
The Four Steps of the Neocloud Playbook
- Secure anchor customers. Sign multi-year agreements with companies like Microsoft and Meta.
- Raise capital against the contracts. Collect prepayments and arrange asset-backed loans.
- Build or lease the capacity. Secure power, buildings, and GPUs on a tight schedule.
- Deliver and bill. Hit delivery dates so revenue starts and lenders stay comfortable.
Step three is where Nebius is currently feeling pressure.
Where the Playbook Shows Cracks: The Vineland Delay
The clearest stress point is a data center in Vineland, New Jersey, where Microsoft is paying for AI computing capacity under a contract worth up to $19.4 billion. The site is now months behind schedule. Only just over half of the Microsoft capacity is planned for delivery by the end of the year, with the remainder pushed to the second quarter of 2027.
What Caused the Delay?
According to Nebius chief product and infrastructure officer Andrey Korolenko, the site’s third-party operator, DataOne, wound down temporary power generation faster than expected as it switched to Bloom Energy fuel cells. The change was not entirely voluntary. In August, the investigative outlet Floodlight reported at least 45 natural gas generators running at the site without permits, and New Jersey regulators fined the facility $1.1 million for violating federal law. DataOne also faces a lawsuit from neighbors over a persistent humming noise.
This is a useful reminder that AI infrastructure runs into very physical problems: power, permits, and neighbors.
What Does the Microsoft Contract Say About Delays?
Based on Nebius’s own summary of the agreement, Microsoft can terminate affected service after a grace period if delivery dates are missed and no alternative capacity is offered. The contract also includes financial penalties for late delivery. The original tranches were meant to be deployed in 2025 and 2026, so a second-quarter 2027 date falls well outside that window.
Nebius said Microsoft has been part of the planning process but did not say whether Microsoft agreed to the new dates. Microsoft has not publicly canceled anything. TechCrunch said it had asked Nebius, Microsoft, and DataOne for comment.
Is Microsoft Pulling Back From Neoclouds?
Bloomberg reported last week that Microsoft is tightening oversight of projects run by third parties, including Nebius, IREN, and Nscale, and is debating whether to sign new agreements. The same reporting said Microsoft will not exercise an option to more than double its Nscale agreement for a Texas site and stopped acting as an anchor customer for a planned Nscale site in Essex after power delays. Microsoft’s own earnings noted that its capital spending came in lower than expected because of third-party delays.
None of this means the relationship is ending. It does show that even the largest buyers are willing to change course when a partner misses dates.
Why Delays Hurt Neocloud Financing More Than Other Models
A delayed site hurts a neocloud twice. Costs keep accumulating because land, equipment, and staff are already committed, while revenue slips because customers are not yet being billed for working capacity.
The Delay Loop
Here is how the loop works in practice:
- A site misses its delivery date because of power, permits, or construction problems.
- Revenue that was forecast for that quarter moves to a later quarter.
- Lenders and customers become more cautious about the next project.
- The company needs more of its own cash to bridge the gap, or must accept worse terms.
This is the core risk in neocloud financing: the mechanism that makes growth affordable is the same one that punishes timing mistakes. Nebius CEO Arkady Volozh acknowledged the issue directly on the call, saying of delays that “We are not immune.”
Why Concentration Makes It Sharper
A small number of customers account for a large share of the backlog. When a single customer such as Microsoft tightens expectations, the effect on the asset-backed collateral and on future prepayments can be significant. Strong customer credit helps lenders, but concentration cuts both ways.
Nebius’s Response: Build Sites It Controls
Nebius argues that the delays are confined to sites it does not control. The company says the data centers it builds itself are coming online on time or ahead of schedule and will supply most of its new capacity starting in 2027. If that holds, the Vineland problem would be a bridge-year issue rather than a structural flaw.
That distinction matters for anyone evaluating neocloud financing as a model. Control over power, construction, and operations reduces one of the biggest risks, but it also raises the amount of capital Nebius must manage directly.
Is Neocloud Financing Sustainable?
Neocloud financing can be sustainable when contracts are with creditworthy customers, delivery dates are met, and capital markets stay open. It becomes fragile when any of those three conditions weakens. The honest answer today is that the model is unproven at this scale, and Nebius’s 2027 plan is one of the biggest tests so far.
The Bull Case
- Customers are paying large amounts in advance, which lowers borrowing needs.
- Investment-grade contracts with Microsoft and Meta make secured lending easier.
- Nebius expects pre-tax break-even by the fourth quarter of 2027 and forecasts $12 billion to $13 billion of 2027 revenue.
- Self-built sites are reported to be on or ahead of schedule.
The Bear Case
- Third-party delays are already cutting 2026 revenue guidance.
- Microsoft is reportedly scrutinizing partners that miss deadlines.
- A large share of third-quarter revenue was a one-time payment, so growth may look stronger than the underlying trend.
- Spending needs of $40 billion to $45 billion dwarf current cash of $7.4 billion.
This article is analysis, not investment advice, and readers should consult primary filings and a licensed advisor before making decisions.
What to Watch Next
If you are tracking whether neocloud financing holds up, these are the indicators that matter most:
- Vineland delivery milestones: whether the first tranche arrives by year-end and the rest in Q2 2027.
- Microsoft’s public posture: any confirmation, amendment, or termination notice tied to delayed capacity.
- Financing closings: whether asset-backed loans against Microsoft and Meta contracts close on expected terms.
- Self-built site progress: whether Nebius-controlled data centers really deliver on time.
- Peer signals: how Nscale, IREN, and CoreWeave handle similar delays and funding needs.
Frequently Asked Questions
How much does Nebius plan to spend in 2027?
Nebius plans $40 billion to $45 billion in capital expenditures for 2027, based on its third-quarter 2026 earnings call.
How will Nebius fund its 2027 spending?
Nebius expects customer prepayments and asset-backed financing to cover up to 85% of the plan, with $7.4 billion in cash as additional support.
Why are neocloud delays such a big deal?
Delays postpone revenue while costs continue, and they can trigger penalties or termination rights in customer contracts, as in Nebius’s agreement with Microsoft.
Is Nebius profitable?
Nebius says it expects to break even on a pre-tax basis by the fourth quarter of 2027. It is not yet there, and third-quarter revenue included a one-time payment.
What is the difference between a neocloud and a hyperscaler?
A neocloud focuses on renting GPU capacity for AI, while a hyperscaler runs a broad cloud and software business and funds construction mostly from its own cash flows.
Bottom Line
Nebius’s $40 billion-plus plan is the clearest live test of whether neocloud financing can carry an AI build-out at this scale. The structure is clever: customers and lenders supply most of the money before the capacity exists. But it only works if the buildings, power, and permits show up on time, and the Vineland delay shows how quickly reality can interrupt a spreadsheet. Watch delivery dates, Microsoft’s behavior, and the closing of secured loans over the next two quarters, because those will show whether the playbook is durable or merely fortunate.
‘ନିଓକ୍ଲାଉଡ୍ ଫାଇନାନ୍ସିଂ’ (Neocloud Financing) ବୁଝାମଣା: AI ଡାଟା ସେଣ୍ଟର ପାଇଁ ୪୦ ବିଲିୟନ ଡଲାର ଯୋଗାଡ଼ କରିବାକୁ ନେବିୟସ୍ (Nebius) ର ଯୋଜନା
‘ନିଓକ୍ଲାଉଡ୍ ଫାଇନାନ୍ସିଂ’ ହେଉଛି ଏକ ଏଭଳି ପଦ୍ଧତି, ଯେଉଁଥିରେ GPU ଡାଟା ସେଣ୍ଟର ନିର୍ମାଣ ପାଇଁ ଆବଶ୍ୟକ ଅର୍ଥ, ସେହି ସୁବିଧା (capacity) ପ୍ରସ୍ତୁତ ହେବା ପୂର୍ବରୁ ଗ୍ରାହକ ଏବଂ ଋଣଦାତାଙ୍କ ଠାରୁ ସଂଗ୍ରହ କରାଯାଏ। ନେବିୟସ୍ (Nebius) ବର୍ତ୍ତମାନ ୨୦୨୭ ମସିହାରେ ହେବାକୁ ଥିବା ପ୍ରାୟ ୪୦ ରୁ ୪୫ ବିଲିୟନ ଡଲାରର ଖର୍ଚ୍ଚ ପାଇଁ ଏହି ପଦ୍ଧତି ଉପରେ ନିର୍ଭର କରୁଛି। ଯଦି ଡାଟା ସେଣ୍ଟରଗୁଡ଼ିକ ନିର୍ଦ୍ଧାରିତ ସମୟ ମଧ୍ୟରେ ପ୍ରସ୍ତୁତ ହୋଇଯାଏ, ତେବେ ଏହି ପଦ୍ଧତି ଅତ୍ୟନ୍ତ ଫଳପ୍ରଦ ହୋଇଥାଏ; କିନ୍ତୁ ଯଦି ବିଳମ୍ବ ହୁଏ, ତେବେ ଖର୍ଚ୍ଚ ଦ୍ରୁତ ଗତିରେ ବଢ଼ିଯାଏ। ୧୨ ନଭେମ୍ବର, ୨୦୨୬ ରେ ଅନୁଷ୍ଠିତ କମ୍ପାନୀର ଆୟ ସମ୍ବନ୍ଧୀୟ ସମୀକ୍ଷା ବୈଠକରେ (earnings call) ନେବିୟସ୍ ଠିକ୍ ଏହି ସମସ୍ୟାକୁ ଉପସ୍ଥାପନ କରିଥିଲା।
ଯଦି ଆପଣ AI ଭିତ୍ତିଭୂମି (AI infrastructure) ଉପରେ ନଜର ରଖନ୍ତି, ତେବେ ଏହି ଘଟଣାଟି ଚଳିତ ତ୍ରୈମାସିକର ଅନ୍ୟତମ ଗୁରୁତ୍ୱପୂର୍ଣ୍ଣ ବିଷୟ ଅଟେ। ନେବିୟସ୍ ଅତ୍ୟନ୍ତ ଦ୍ରୁତ ଅଭିବୃଦ୍ଧି ହାସଲ କରିଥିଲା, କିନ୍ତୁ ପରବର୍ତ୍ତୀ ସମୟରେ ଗୋଟିଏ ଦିନ ମଧ୍ୟରେ ଏହାର ସେୟାର ମୂଲ୍ୟ ୧୭% ହ୍ରାସ ପାଇଲା। ଏହାର କାରଣ ହେଲା, କମ୍ପାନୀ ଯେଉଁ ଉପାୟରେ ଏହି ଅଭିବୃଦ୍ଧି ପାଇଁ ଅର୍ଥ ଯୋଗାଡ଼ କରୁଛି, ତାହା ବର୍ତ୍ତମାନ ସର୍ବସାଧାରଣରେ ଏକ କଠିନ ପରୀକ୍ଷାର ସମ୍ମୁଖୀନ ହେଉଛି। ଏହି ଲେଖାରେ ବର୍ଣ୍ଣନା କରାଯାଇଛି ଯେ ପ୍ରକୃତରେ କ’ଣ ଘଟିଛି, ଅର୍ଥ ପ୍ରବାହ କିପରି ହେବା କଥା ଏବଂ କେଉଁ କାରଣରୁ ଏହି ବ୍ୟବସ୍ଥା ବିଫଳ ହୋଇପାରେ।
ମୁଖ୍ୟ ବିଷୟଗୁଡ଼ିକ
‘ଟେକକ୍ରଞ୍ଚ’ (TechCrunch) ଏବଂ ‘ରଏଟର୍ସ’ (Reuters) ର ରିପୋର୍ଟ ଅନୁଯାୟୀ, ନେବିୟସ୍ ୨୦୨୭ ମସିହାରେ ପ୍ରାୟ ୪୦ ରୁ ୪୫ ବିଲିୟନ ଡଲାର ପୁଞ୍ଜି ଖର୍ଚ୍ଚ କରିବାକୁ ଯୋଜନା କରିଛି, ଯାହା ‘ୱାଲ୍ ଷ୍ଟ୍ରିଟ୍’ (Wall Street) ର ଆକଳନ ଠାରୁ ବହୁତ ଅଧିକ।
କମ୍ପାନୀ ଆଶା କରୁଛି ଯେ ଗ୍ରାହକଙ୍କ ଠାରୁ ମିଳୁଥିବା ଅଗ୍ରୀମ ଅର୍ଥ (prepayments) ଏ ଏହାର କାରଣ ହେଉଛି, AI କ୍ଷମତା ବିକାଶ କରିବା ପାଇଁ ଆରମ୍ଭରେ ଅନେକ ବିଲିୟନ ଡଲାର ଖର୍ଚ୍ଚ ହୋଇଥାଏ, କିନ୍ତୁ ଏଥିରୁ ମିଳୁଥିବା ଆୟ ବହୁ-ବର୍ଷୀୟ ଚୁକ୍ତିନାମା ମାଧ୍ୟମରେ ଧୀରେ ଧୀରେ ଆସିଥାଏ।
ଅନ୍ୟ ଅର୍ଥରେ କହିଲେ, ଏକ ‘ନିଓକ୍ଲାଉଡ୍’ (neocloud) ଭବିଷ୍ୟତର କମ୍ପ୍ୟୁଟିଂ କ୍ଷମତା ବିକ୍ରି କରେ ଏବଂ ସେହି ବିକ୍ରିର ପ୍ରତିଶ୍ରୁତିକୁ ଆଧାର କରି ଏହାକୁ ପ୍ରସ୍ତୁତ କରିବା ପାଇଁ ଆବଶ୍ୟକ ପୁଞ୍ଜି ସଂଗ୍ରହ କରେ। ଏଠାରେ ଋଣଦାତା କିମ୍ବା ଗ୍ରାହକ ପ୍ରକୃତରେ ଏକ ଚୁକ୍ତିନାମାକୁ ସମର୍ଥନ (underwriting) କରୁଥାନ୍ତି, ନା କି କମ୍ପାନୀର ପୂର୍ବ ଲାଭର ଇତିହାସକୁ।
‘ନିଓକ୍ଲାଉଡ୍’ (Neocloud) କ’ଣ?
‘ନିଓକ୍ଲାଉଡ୍’ ହେଉଛି ଏକ ପ୍ରକାର କ୍ଲାଉଡ୍ ସେବା ପ୍ରଦାନକାରୀ, ଯାହା ବିଭିନ୍ନ ପ୍ରକାରର ସଫ୍ଟୱେର୍ ସେବା ଯୋଗାଇବା ପରିବର୍ତ୍ତେ, ମୁଖ୍ୟତଃ AI କାର୍ଯ୍ୟଭାର (workloads) ପାଇଁ GPU କମ୍ପ୍ୟୁଟିଂ କ୍ଷମତା ଭଡ଼ାରେ ଦେବା ଉପରେ ଧ୍ୟାନ କେନ୍ଦ୍ରିତ କରିଥାଏ। ଗବେଷଣା ସଂସ୍ଥା ‘ସେମି-ଆନାଲିସିସ୍’ (SemiAnalysis) – ଯାହା ନିଜର “AI ନିଓକ୍ଲାଉଡ୍ ପ୍ଲେବୁକ୍” (AI Neocloud Playbook) ମାଧ୍ୟମରେ ଏହି ଶବ୍ଦକୁ ଲୋକପ୍ରିୟ କରିଥିଲା - ଏହାକୁ ଏକ ନୂତନ ଶ୍ରେଣୀର ସେବା ପ୍ରଦାନକାରୀ ଭାବରେ ବର୍ଣ୍ଣନା କରିଛି, ଯାହାର ମୁଖ୍ୟ ଲକ୍ଷ୍ୟ ହେଉଛି GPU କମ୍ପ୍ୟୁଟ୍ କ୍ଷମତା ଭଡ଼ାରେ ଦେବା। ‘ସିନର୍ଜି ରିସର୍ଚ୍ଚ ଗ୍ରୁପ୍’ (Synergy Research Group) ର ଆକଳନ ଅନୁଯାୟୀ, ୨୦୨୫ ମସିହାରେ ଏହି କ୍ଷେତ୍ରରୁ ୨୫ ବିଲିୟନ ଡଲାରରୁ ଅଧିକ ଆୟ ହୋଇଥିଲା।
‘ନେବିୟସ୍’ (Nebius) ହେଉଛି ଏହାର ଅନ୍ୟତମ ପ୍ରମୁଖ ଉଦାହରଣ। ଆମଷ୍ଟରଡାମ୍-ଭିତ୍ତିକ ଏହି କମ୍ପାନୀଟି ‘ୟାଣ୍ଡେକ୍ସ’ (Yandex) ର ଆନ୍ତର୍ଜାତୀୟ କାର୍ଯ୍ୟକଳାପରୁ ଅଲଗା ହୋଇ ଗଠିତ ହୋଇଥିଲା ଏବଂ ମାଇକ୍ରୋସଫ୍ଟ (Microsoft) ତଥା ମେଟା (Meta) ଭଳି ବଡ଼ କମ୍ପାନୀଗୁଡ଼ିକ ଏହାର ପ୍ରମୁଖ ଗ୍ରାହକ ଅଟନ୍ତି।
‘ନିଓକ୍ଲାଉଡ୍’ ପାଇଁ ପାଣ୍ଠି ସଂଗ୍ରହ ପ୍ରକ୍ରିୟା, ‘ହାଇପରସ୍କେଲର୍’ (hyperscaler) ମାନଙ୍କ ଠାରୁ କିପରି ଭିନ୍ନ?
ମାଇକ୍ରୋସଫ୍ଟ, ଆମାଜନ୍ ଏବଂ ଗୁଗୁଲ୍ ଭଳି ‘ହାଇପରସ୍କେଲର୍’ କମ୍ପାନୀଗୁଡ଼ିକ ନିଜର ଡାଟା ସେଣ୍ଟର ପାଇଁ ଆବଶ୍ୟକ ଅର୍ଥ ମୁଖ୍ୟତଃ ନିଜର ବିପୁଳ ପରିଚାଳନାଗତ ନଗଦ ପ୍ରବା ନେବିୟସ୍ (Nebius) ନିଜର ତୃତୀୟ ତ୍ରୈମାସିକ ଆୟ ସମ୍ବନ୍ଧୀୟ ଆଲୋଚନା (earnings call) ସମୟରେ ୨୦୨୭ ମସିହା ପାଇଁ ଏକ ଯୋଜନା ଉପସ୍ଥାପନ କରିଛି। ଏହି ଯୋଜନା ଅନୁଯାୟୀ, କମ୍ପାନୀ ୪୦ ବିଲିୟନ ଡଲାରରୁ ୪୫ ବିଲିୟନ ଡଲାର ପୁଞ୍ଜିଗତ ବ୍ୟୟ (capital expenditure) କରିବ।
ଏହା ସହିତ, ୨୦୨୭ ମସିହାରେ ୧୨ ବିଲିୟନ ଡଲାରରୁ ୧୩ ବିଲିୟନ ଡଲାର ଆୟ ହେବାର ପୂର୍ବାନୁମାନ କରାଯାଇଛି ଏବଂ ଚତୁର୍ଥ ତ୍ରୈମାସିକ ସୁଦ୍ଧା କମ୍ପାନୀ କର-ପୂର୍ବ ଲାଭ-କ୍ଷତି ସମାନ ସ୍ତରକୁ (break-even) ଆସିବ ବୋଲି ଆଶା କରାଯାଉଛି। ‘ଡିଗ୍’ (Digg) ଦ୍ୱାରା ସାରାଂଶିତ ‘ରଏଟର୍ସ’ (Reuters) ରିପୋର୍ଟ ଅନୁଯାୟୀ, ୨୦୨୬ ମସିହା ପାଇଁ ବ୍ୟୟ ଅଟକଳକୁ ପୂର୍ବର ୨୦-୨୫ ବିଲିୟନ ଡଲାରରୁ ବୃଦ୍ଧି କରି ପ୍ରାୟ ୨୭ ବିଲିୟନ ଡଲାର କରାଯାଇଛି।
ନେବିୟସ୍ର ଏହି ବୃହତ ପୁଞ୍ଜିଗତ ବ୍ୟୟ (capex) ପଛର ମୁଖ୍ୟ କାରଣ ହେଉଛି AI (କୃତ୍ରିମ ବୁଦ୍ଧିମତ୍ତା) ଗ୍ରାହକମାନଙ୍କ ଠାରୁ ରହିଥିବା ଅତ୍ୟଧିକ ଚାହିଦା। ଏହା ସହିତ, କମ୍ପାନୀ ଏଭଳି ଅଂଶୀଦାରମାନଙ୍କୁ ପାଇବା ନେଇ ଆଶା ରଖିଛି ଯେଉଁମାନେ ଆଗୁଆ ଅର୍ଥ ପ୍ରଦାନ କରିବାକୁ ପ୍ରସ୍ତୁତ ଅଛନ୍ତି।
ସଂକ୍ଷେପରେ କିଛି ଗୁରୁତ୍ୱପୂର୍ଣ୍ଣ ତଥ୍ୟ:
ବିବରଣୀ | ଉପସ୍ଥାପିତ ସଂଖ୍ୟା
୨୦୨୭ ପୁଞ୍ଜିଗତ ବ୍ୟୟ ଯୋଜନା | ୪୦ ବିଲିୟନ ଡଲାରରୁ ୪୫ ବିଲିୟନ ଡଲାର
୨୦୨୭ ଆୟ ପୂର୍ବାନୁମାନ | ୧୨ ବିଲିୟନ ଡଲାରରୁ ୧୩ ବିଲିୟନ ଡଲାର
ଆଗୁଆ ଦେୟ ଏବଂ ସମ୍ପତ୍ତି-ଆଧାରିତ ଆର୍ଥିକ ସହାୟତା ଦ୍ୱାରା ପୂରଣ ହେବାକୁ ଥିବା ୨୦୨୭ ପୁଞ୍ଜିଗତ ବ୍ୟୟର ଅଂଶ | ୮୫% ପର୍ଯ୍ୟନ୍ତ
୨୦୨୬ ତୃତୀୟ ତ୍ରୈମାସିକ ଆୟ | ୯୮୧ ନିୟୁତ ଡଲାର (ଗତ ବର୍ଷ ତୁଳନାରେ ୫୭୧% ଅଧିକ)
ତ୍ରୈମାସିକ ଶେଷରେ ନଗଦ ରାଶି | ୭.୪ ବିଲିୟନ ଡଲାର
ସଂଶୋଧିତ ୨୦୨୬ ଆୟ ପୂର୍ବାନୁମାନ | ୩ ବିଲିୟନ ଡଲାର (୨୦୦ ନିୟୁତ ଡଲାର ହ୍ରାସ କରାଯାଇଛି)
ମାଇକ୍ରୋସଫ୍ଟ (Microsoft) ଚୁକ୍ତିନାମା ମୂଲ୍ୟ | ୧୯.୪ ବିଲିୟନ ଡଲାର ପର୍ଯ୍ୟନ୍ତ
ସେୟାର ମୂଲ୍ୟ ଉପରେ ପ୍ରଭାବ | ସେହି ଦିନ ୧୭% ହ୍ରାସ ପାଇଲା
ଆୟ ସମ୍ବନ୍ଧୀୟ ଏକ ବିଶେଷ ଟିପ୍ପଣୀ: ତୃତୀୟ ତ୍ରୈମ…ଏବଂ ଏକ ବହୁତ ବଡ଼ ବ୍ୟୟ ଯୋଜନା। ରଏଟର୍ସ (Reuters) ରିପୋର୍ଟ କରିଛି ଯେ କ୍ଷମତା (capacity) ପ୍ରସ୍ତୁତିରେ ବିଳମ୍ବ ହେତୁ କିଛି ସମ୍ଭାବ୍ୟ ବିକ୍ରି ୨୦૨୭ ମସିହା ପର୍ଯ୍ୟନ୍ତ ଘୁଞ୍ଚିଯାଇଛି। ଫଳସ୍ୱରୂପ, ନେବିୟସ୍ (Nebius) ବର୍ତ୍ତମାନ ଆଶା କରୁଛି ଯେ ଏହାର ବାର୍ଷିକ ୭ ବିଲିୟନ ଡଲାର ଆୟ ଲକ୍ଷ୍ୟ (annual run-rate revenue target) ହାସଲ କରିବା ପାଇଁ ଯୋଜନା ଠାରୁ ପ୍ରାୟ ଦୁଇ ମାସ ଅଧିକ ସମୟ ଲାଗିପାରେ। ଯେତେବେଳେ ଆୟ ହ୍ରାସ ପାଉଥାଏ ଏବଂ ଖର୍ଚ୍ଚ ବୃଦ୍ଧି ପାଉଥାଏ, ସେତେବେଳେ ବଜାରରେ ପ୍ରଶ୍ନ ଉଠେ ଯେ ଏହି ଅଭାବ କିମ୍ବା ଫାଙ୍କକୁ କିପରି ପୂରଣ କରାଯିବ?
ନେବିୟସ୍ ୪୦ ରୁ ୪୫ ବିଲିୟନ ଡଲାରର ଖର୍ଚ୍ଚ ପାଇଁ କିପରି ଅର୍ଥ ଯୋଗାଡ଼ କରିବାକୁ ଯୋଜନା କରୁଛି?
ନେବିୟସ୍ ମୁଖ୍ୟତଃ ଗ୍ରାହକଙ୍କଠାରୁ ମିଳୁଥିବା ଅଗ୍ରୀମ ଅର୍ଥରାଶି (prepayments) ଏବଂ ସମ୍ପତ୍ତି-ଆଧାରିତ ଆର୍ଥିକ ବ୍ୟବସ୍ଥା (asset-backed financing) ମାଧ୍ୟମରେ ଏହି ଖର୍ଚ୍ଚ ବହନ କରିବାକୁ ଯୋଜନା କରୁଛି; ଏଥିସହ କମ୍ପାନୀ ପାଖରେ ଥିବା ନଗଦ ଅର୍ଥ ମଧ୍ୟ ଏକ ସୁରକ୍ଷା କବଚ ଭାବରେ କାମ କରିବ। ପରିଚାଳନା କର୍ତ୍ତୃପକ୍ଷଙ୍କ କହିବା ଅନୁଯାୟୀ, ଏହି ଉତ୍ସଗୁଡ଼ିକ ମିଳିତ ଭାବରେ ୨୦୨୭ ମସିହାର ପୁଞ୍ଜି ବଜେଟର (capital budget) ୮୫% ପର୍ଯ୍ୟନ୍ତ ଅର୍ଥ ଯୋଗାଇପାରେ। ରଏଟର୍ସ ଅନୁଯାୟୀ, ଏହି ପରିମାଣ ୭୫% ରୁ ୮୫% ମଧ୍ୟରେ ରହିପାରେ।
ଏହି ପ୍ରକ୍ରିୟାର ବିଭିନ୍ନ ଦିଗଗୁଡ଼ିକ ନିମ୍ନରେ ବର୍ଣ୍ଣନା କରାଯାଇଛି:
ଗ୍ରାହକଙ୍କଠାରୁ ଅଗ୍ରୀମ ଅର୍ଥରାଶି (Customer Prepayments)
ଗ୍ରାହକମାନେ ଯେଉଁ କ୍ଷମତା (capacity) କିଣିଥାନ୍ତି, ତାହା ହସ୍ତାନ୍ତର ହେବା ପୂର୍ବରୁ ସେମାନେ ଯେଉଁ ଅର୍ଥ ପ୍ରଦାନ କରନ୍ତି, ତାହାକୁ ‘ଅଗ୍ରୀମ ଅର୍ଥରାଶି’ କୁହାଯାଏ। ନେବିୟସ୍ର ମୁଖ୍ୟ ରାଜସ୍ୱ ଅଧିକାରୀ (Chief Revenue Officer) ମାର୍କ ବୋରୋଡିଟସ୍କି କହିଛନ୍ତି ଯେ ମାଇକ୍ରୋସଫ୍ଟ (Microsoft) ଏବଂ ମେଟା (Meta) ସହ ହୋଇଥିବା ଚୁକ୍ତିଗୁଡ଼ିକରେ ବହୁତ ପୂର୍ବରୁ ମିଳିଥିବା ବଡ଼ ଧରଣର ଅଗ୍ରୀମ ଅର୍ଥରାଶି ଅନ୍ତର୍ଭୁକ୍ତ ଥିଲା। ସେହିପରି, ତୃତୀୟ ତ୍ରୈମାସିକରେ ସ୍ୱାକ୍ଷରିତ ହୋଇଥିବା ନୂତନ ଚୁକ୍ତିଗୁଡ଼ିକରେ ମଧ୍ୟ ଏପରି ଅଗ୍ରୀମ ଅର୍ଥରାଶି ରହିଛି, ଯାହା ସେହି ଚୁକ୍ତି ସହ ଜଡ଼ିତ କ୍ଷମତା ପ୍ରସ୍ତୁତି ଖର୍ଚ୍ଚ ହସ୍ତଗତ ନଗଦ ରାଶି (Cash on Hand)
ତ୍ରୈମାସିକ ଶେଷ ସୁଦ୍ଧା Nebius ପାଖରେ ୭.୪ ବିଲିୟନ ଡଲାର ନଗଦ ଅର୍ଥ ଥିଲା। ଏହା ଏକ ଗୁରୁତ୍ୱପୂର୍ଣ୍ଣ ପରିମାଣ ହେଲେ ମଧ୍ୟ, ୪୦ ବିଲିୟନ ଡଲାରରୁ ଅଧିକ ମୂଲ୍ୟର ବାର୍ଷିକ ଯୋଜନା ତୁଳନାରେ ଏହା ବହୁତ କମ୍। ତେଣୁ କମ୍ପାନୀ କହିଛି ଯେ, ଅତିରିକ୍ତ ନଗଦ ଅର୍ଥର ଆବଶ୍ୟକତା ପଡ଼ିଲେ ସେମାନେ ଗ୍ରାହକଙ୍କଠାରୁ ମିଳୁଥିବା ‘ଅଗ୍ରୀମ ପୈଠ’ (prepayments) ର ସହାୟତା ନେଇପାରନ୍ତି।
‘ନିଓକ୍ଲାଉଡ୍’ (Neocloud) ପାଇଁ ପାଣ୍ଠି ସଂଗ୍ରହର ବିଭିନ୍ନ ଉତ୍ସର ତୁଳନା
ପାଣ୍ଠି ସଂଗ୍ରହର ବିଭିନ୍ନ ଉତ୍ସ ସହିତ ଭିନ୍ନ ଭିନ୍ନ ଖର୍ଚ୍ଚ ଏବଂ ଆର୍ଥିକ ବିପଦ (risks) ଜଡ଼ିତ ଥାଏ। ନିମ୍ନରେ ଦିଆଯାଇଥିବା ସାରଣୀଟି ଏକ ବିଶ୍ଳେଷଣାତ୍ମକ ତୁଳନା ଅଟେ; ଏହା Nebius ର ନିଜସ୍ୱ ସର୍ତ୍ତାବଳୀର ବିବରଣୀ ନୁହେଁ।
ପାଣ୍ଠି ଉତ୍ସ | ଗତି | ଅଂଶୀଦାରମାନଙ୍କ (shareholders) ଉପରେ ପ୍ରଭାବ | ମୁଖ୍ୟ ବିପଦ
ଗ୍ରାହକଙ୍କ ଅଗ୍ରୀମ ପୈଠ | ଦ୍ରୁତ (ଚୁକ୍ତିନାମା ସ୍ୱାକ୍ଷର ଉପରେ ନିର୍ଭରଶୀଳ) | କିଛି ନାହିଁ | ସେବା ଯୋଗାଣରେ ବିଳମ୍ବ ହେଲେ ଜରିମାନା କିମ୍ବା ଚୁକ୍ତି ରଦ୍ଦ ହେବାର ଆଶଙ୍କା
ସମ୍ପତ୍ତି-ଆଧାରିତ ଋଣ (Asset-backed financing) | ମଧ୍ୟମ (ଚୁକ୍ତିନାମା ଆବଶ୍ୟକ) | କିଛି ନାହିଁ | ଚୁକ୍ତିନାମାରେ ପରିବର୍ତ୍ତନ ଆସିଲେ ବନ୍ଧକ ରଖାଯାଇଥିବା ସମ୍ପତ୍ତିର ମୂଲ୍ୟ କମିଯାଇପାରେ
ଇକ୍ୱିଟି (ଅଂଶଧନ) ଜାରି କରିବା | ବଜାର ଖୋଲା ଥିଲେ ଦ୍ରୁତ | ହଁ | ସେୟାର ମୂଲ୍ୟ କମିଗଲେ ଏହା ଅଧିକ ବ୍ୟୟବହୁଳ ହୋଇଯାଏ
ଅସୁରକ୍ଷିତ ଋଣ (Unsecured debt) | କ୍ରେଡିଟ୍ ବଜାର ଉପରେ ନିର୍ଭରଶୀଳ | କିଛି ନାହିଁ | ସ୍ୱତନ୍ତ୍ର ଆୟର ଉତ୍ସ ନଥିଲେ ଏହା ପାଇବା କଷ୍ଟକର ହୋଇଥାଏ
ଏଠାରେ ଏକ ସ୍ପଷ୍ଟ ଧାରା ଦେଖାଯାଏ: ‘ନିଓକ୍ଲାଉଡ୍’ କ୍ଷେତ୍ରରେ ଯେଉଁ ଉତ୍ସଗୁଡ଼ିକରୁ ସବୁଠାରୁ ଶସ୍ତାରେ ପାଣ୍ଠି ମିଳିଥାଏ, ସେଗୁଡ଼ିକ ହିଁ ସେବା ଯୋଗାଣ କ୍ଷମତା (delivery performance) ଉପରେ ସବୁଠାରୁ ଅଧିକ ନିର୍ଭରଶୀଳ ହୋଇଥାଏ।
‘ନିଓକ୍ଲାଉଡ୍ ପ୍ଲେବୁକ୍’ (Neocloud Playbook) କ’ଣ?
‘ନିଓକ୍ଲାଉଡ୍ ପ୍ଲେବୁକ୍’ ହେଉଛି ଏକ ପୁନରାବୃତ୍ତିଯୋଗ୍ୟ ବିକାଶ ରଣନୀତି: ବଡ଼ AI ଗ୍ରାହକମାନଙ୍କ ସହିତ ଦୀର୍ଘମିଆଦି ଚୁକ୍ତି ବର୍ଷ ଶେଷ ସୁଦ୍ଧା ମାଇକ୍ରୋସଫ୍ଟ କ୍ଷମତାର ମାତ୍ର ଅଧାରୁ ଅଧିକ ବିତରଣ ପାଇଁ ଯୋଜନା କରାଯାଇଛି, ଅବଶିଷ୍ଟ 2027 ର ଦ୍ୱିତୀୟ ତ୍ରୟମାସକୁ ଠେଲି ଦିଆଯିବ।
ବିଳମ୍ବର କାରଣ କ’ଣ?
ନେବିଅସ୍ ମୁଖ୍ୟ ଉତ୍ପାଦ ଏବଂ ଭିତ୍ତିଭୂମି ଅଧିକାରୀ ଆଣ୍ଡ୍ରେ କୋରୋଲେଙ୍କୋଙ୍କ ଅନୁଯାୟୀ, ସାଇଟର ତୃତୀୟ-ପକ୍ଷ ଅପରେଟର, ଡାଟାୱାନ୍, ବ୍ଲୁମ୍ ଏନର୍ଜି ଇନ୍ଧନ ସେଲ୍ସକୁ ସ୍ୱିଚ୍ କରିବା ସହିତ ଆଶାଠାରୁ ଅଧିକ ଦ୍ରୁତ ଗତିରେ ଅସ୍ଥାୟୀ ବିଦ୍ୟୁତ୍ ଉତ୍ପାଦନକୁ ବନ୍ଦ କରିଦେଇଥିଲା। ଏହି ପରିବର୍ତ୍ତନ ସମ୍ପୂର୍ଣ୍ଣ ସ୍ୱେଚ୍ଛାକୃତ ନଥିଲା। ଅଗଷ୍ଟରେ, ତଦନ୍ତକାରୀ ଆଉଟଲେଟ୍ ଫ୍ଲଡଲାଇଟ୍ ରିପୋର୍ଟ କରିଥିଲା ଯେ ଅନୁମତି ବିନା ସାଇଟରେ ଅତି କମରେ 45ଟି ପ୍ରାକୃତିକ ଗ୍ୟାସ ଜେନେରେଟର ଚାଲୁଛି, ଏବଂ ନ୍ୟୁ ଜର୍ସି ନିୟାମକମାନେ ଫେଡେରାଲ୍ ଆଇନ ଉଲ୍ଲଂଘନ କରିବା ପାଇଁ ସୁବିଧାକୁ $1.1 ନିୟୁତ ଜରିମାନା କରିଥିଲେ। ଡାଟାୱାନ୍ ମଧ୍ୟ ଏକ ନିରନ୍ତର ଗୁଞ୍ଜରିତ ଶବ୍ଦ ପାଇଁ ପଡ଼ୋଶୀମାନଙ୍କଠାରୁ ଏକ ମାମଲା ସାମ୍ନା କରେ।
ଏହା ଏକ ଉପଯୋଗୀ ସ୍ମରଣକାରୀ ଯେ AI ଭିତ୍ତିଭୂମି ବହୁତ ଭୌତିକ ସମସ୍ୟାରେ ପଡ଼ିଥାଏ: ଶକ୍ତି, ଅନୁମତି ଏବଂ ପଡ଼ୋଶୀମାନେ।
ବିଳମ୍ବ ସମ୍ବନ୍ଧରେ ମାଇକ୍ରୋସଫ୍ଟ ଚୁକ୍ତିନାମାରେ କ’ଣ କୁହାଯାଇଛି?
ଚୁକ୍ତିନାମା ସମ୍ପର୍କରେ ନେବିୟସ୍ (Nebius) ଦେଇଥିବା ସାରାଂଶ ଅନୁଯାୟୀ, ଯଦି ନିର୍ଦ୍ଧାରିତ ସମୟ ମଧ୍ୟରେ ସେବା ଉପଲବ୍ଧ ନ ହୁଏ ଏବଂ କୌଣସି ବିକଳ୍ପ ବ୍ୟବସ୍ଥା ମଧ୍ୟ ଯୋଗାଇ ଦିଆ ନ ଯାଏ, ତେବେ ଏକ ନିର୍ଦ୍ଦିଷ୍ଟ ଅତିରିକ୍ତ ସମୟସୀମା (grace period) ପରେ ମାଇକ୍ରୋସଫ୍ଟ ସେହି ସେବାକୁ ବନ୍ଦ କରିପାରିବ। ଏହି ଚୁକ୍ତିନାମାରେ ବିଳମ୍ବିତ ସେବା ଯୋଗାଣ ପାଇଁ ଆର୍ଥିକ ଦଣ୍ଡବିଧାନର ବ୍ୟବସ୍ଥା ମଧ୍ୟ ରହିଛି। ପ୍ରାରମ୍ଭିକ ପର୍ଯ୍ୟାୟଗୁଡ଼ିକ ୨୦୨୫ ଏବଂ ୨୦૨୬ ମସିହାରେ କାର୍ଯ୍ୟକାରୀ ହେବାର ଥିଲା, ତେଣୁ ୨୦୨୭ ମସିହାର ଦ୍ୱିତୀୟ ତ୍ରୈମାସିକ ସମୟସୀମାଟି ସେହି ନିର୍ଦ୍ଧାରିତ ଅବଧି ବାହାରେ ରହିଛି।
ନେବିୟସ୍ କହିଛି ଯେ ମାଇକ୍ରୋସଫ୍ଟ ଯୋଜନା ପ୍ରକ୍ରିୟାରେ ସାମିଲ ଥିଲା, କିନ୍ତୁ ମାଇକ୍ରୋସଫ୍ଟ ଏହି ନୂତନ ତାରିଖଗୁଡ଼ିକ ପାଇଁ ସହମତ ହୋଇଛି କି ନାହିଁ, ସେ ବିଷୟରେ କିଛି କହିନାହିଁ। ମାଇକ୍ରୋସଫ୍ଟ ସର୍ବସାଧାରଣରେ କୌଣସି ଚୁକ୍ତି ବାତିଲ କରିନାହିଁ। ‘ଟେକ୍କ୍ରଞ୍ଚ’ (TechCrunch) ଜଣାଇଛି ଯେ ସେମାନେ ନେବିୟସ୍, ମାଇକ୍ରୋସଫ୍ଟ ଏବଂ ଡାଟାୱାନ୍ (DataOne) ଠାରୁ ଏ ବିଷୟରେ ମତାମତ ଲୋଡ଼ିଥିଲେ।
ମାଇକ୍ରୋସଫ୍ଟ କ’ଣ ‘ନିଓକ୍ଲାଉଡ୍’ (Neoclouds) ପ୍ରକଳ୍ପଗୁଡ଼ିକରୁ ନିଜକୁ ଦୂରେଇ ନେଉଛି?
ଗତ ସପ୍ତାହରେ ‘ବ୍ଲୁମବର୍ଗ’ (Bloomberg) ରିପୋର୍ଟ କରିଥିଲା ଯେ ମାଇକ୍ରୋସଫ୍ଟ, ନେବିୟସ୍, IREN ଏବଂ Nscale ଭଳି ତୃତୀୟ ପକ୍ଷ ଦ୍ୱାରା ପରିଚାଳିତ ପ୍ରକଳ୍ପଗୁଡ଼ିକ ଉପରେ ନିଜର ତଦାରଖ କଡ଼ାକଡ଼ି କରୁଛି ଏବଂ ନୂତନ ଚୁକ୍ତିନାମା ସ୍ୱାକ୍ଷର କରିବ କି ନାହିଁ ସେ ନେଇ ବିଚାରବିମର୍ଶ କରୁଛି। ସେହି ରିପୋର୍ଟ ଅନୁଯାୟୀ, ଟେକ୍ସାସ୍ରେ ଥିବା Nscale ପ୍ରକଳ୍ପ ପାଇଁ ଥିବା ଚୁକ୍ତିନାମାକୁ ଦ୍ୱିଗୁଣିତ କରିବାର ବିକଳ୍ପକୁ ମାଇକ୍ରୋସଫ୍ଟ ବ୍ୟବହାର କରିବ ନାହିଁ। ଏହା ବ୍ୟତୀତ, ବିଦ୍ୟୁତ୍ ଯୋଗାଣରେ ବିଳମ୍ବ ହେତୁ ଏସେକ୍ସ (Essex) ରେ ଯୋଜନା କରାଯାଇଥିବା Nscale ପ୍ରକଳ୍ପ ପାଇଁ ମାଇକ୍ରୋସଫ୍ଟ ଏକ ‘ମୁଖ୍ୟ ଗ୍ରାହକ’ (anchor customer) ଭୂମିକାରୁ ଓହରି ଯାଇଛି।
ମାଇକ୍ରୋସଫ୍ଟର ନିଜସ୍ୱ ଆୟ ବିବ ‘ନିଓକ୍ଲାଉଡ୍’ (neocloud) ଆର୍ଥିକ ମଡେଲରେ ଏହା ହେଉଛି ମୁଖ୍ୟ ବିପଦ: ଯେଉଁ ବ୍ୟବସ୍ଥା ଅଭିବୃଦ୍ଧିକୁ ସୁଲଭ କରିଥାଏ, ଠିକ୍ ସେହି ବ୍ୟବସ୍ଥା ହିଁ ସମୟ ନିର୍ଦ୍ଧାରଣରେ (timing) ଭୁଲ୍ ହେଲେ କ୍ଷତି ପହଞ୍ଚାଇଥାଏ। ‘ନେବିୟସ୍’ (Nebius) ର ସିଇଓ ଆର୍କାଡି ଭୋଲୋଜ୍ ଏକ ଆଲୋଚନା ସମୟରେ ଏହି ସମସ୍ୟାକୁ ସ୍ୱୀକାର କରିଛନ୍ତି ଏବଂ ବିଳମ୍ବ ସମ୍ପର୍କରେ କହିଛନ୍ତି ଯେ, “ଆମେ ମଧ୍ୟ ଏଥିରୁ ମୁକ୍ତ ନୁହଁୁ (ଅର୍ଥାତ୍ ଆମ ଉପରେ ମଧ୍ୟ ଏହାର ପ୍ରଭାବ ପଡ଼ିପାରେ)।”
ଗ୍ରାହକଙ୍କ କେନ୍ଦ୍ରୀଭୂତ ହେବା (Concentration) କିପରି ବିପଦକୁ ବଢ଼ାଇଥାଏ
କମ୍ ସଂଖ୍ୟକ ଗ୍ରାହକଙ୍କ ପାଖରେ ବହୁତ ବଡ଼ ପରିମାଣର କାର୍ଯ୍ୟଭାର (backlog) ରହିଛି। ଯେତେବେଳେ ମାଇକ୍ରୋସଫ୍ଟ (Microsoft) ଭଳି କୌଣସି ଏକ ବଡ଼ ଗ୍ରାହକ ନିଜର ଆଶା ବା ସର୍ତ୍ତକୁ କଠୋର କରିଦିଅନ୍ତି, ସେତେବେଳେ ଏହାର ପ୍ରଭାବ ସମ୍ପତ୍ତି-ଆଧାରିତ ଜମାନତ (collateral) ଏବଂ ଭବିଷ୍ୟତର ଅଗ୍ରୀମ ଦେୟ ଉପରେ ଗୁରୁତର ପଡ଼ିପାରେ। ଗ୍ରାହକଙ୍କ ଆର୍ଥିକ ବିଶ୍ୱସନୀୟତା ଋଣଦାତାଙ୍କ ପାଇଁ ସହାୟକ ହୁଏ, କିନ୍ତୁ ଗ୍ରାହକଙ୍କ କେନ୍ଦ୍ରୀଭୂତ ହେବା (ଯେତେବେଳେ ଅଳ୍ପ କିଛି ଗ୍ରାହକଙ୍କ ଉପରେ ଅତ୍ୟଧିକ ନିର୍ଭରଶୀଳତା ଥାଏ) ଉଭୟ ସକାରାତ୍ମକ ଓ ନକାରାତ୍ମକ ପ୍ରଭାବ ପକାଇପାରେ।
ନେବିୟସ୍ର ପଦକ୍ଷେପ: ନିଜ ନିୟନ୍ତ୍ରଣାଧୀନ କେନ୍ଦ୍ର ନିର୍ମାଣ କରିବା
ନେବିୟସ୍ ଯୁକ୍ତି କରେ ଯେ, ବିଳମ୍ବ କେବଳ ସେହି କେନ୍ଦ୍ରଗୁଡ଼ିକରେ ହେଉଛି ଯାହା ଉପରେ କମ୍ପାନୀର ନିୟନ୍ତ୍ରଣ ନାହିଁ। କମ୍ପାନୀ କହିଛି ଯେ, ଯେଉଁ ଡାଟା ସେଣ୍ଟରଗୁଡ଼ିକୁ ସେ ନିଜେ ନିର୍ମାଣ କରୁଛି, ସେଗୁଡ଼ିକ ନିର୍ଦ୍ଧାରିତ ସମୟରେ କିମ୍ବା ତା’ଠାରୁ ଆଗୁଆ କାର୍ଯ୍ୟକ୍ଷମ ହେଉଛି। ୨୦୨୭ ମସିହାରୁ ଏହି କେନ୍ଦ୍ରଗୁଡ଼ିକ କମ୍ପାନୀର ଅଧିକାଂଶ ନୂତନ କ୍ଷମତା (capacity) ଯୋଗାଇବେ। ଯଦି ଏହା ସତ ହୁଏ, ତେବେ ‘ଭାଇନଲ୍ୟାଣ୍ଡ’ (Vineland) ସମସ୍ୟାଟି ଏକ ସ୍ଥାୟୀ ତ୍ରୁଟି ନ ହୋଇ କେବଳ ଏକ ସଂକ୍ରମଣକାଳୀନ (transition period) ସମସ୍ୟା ହୋଇ ରହିବ।
ଏହି ପାର୍ଥକ୍ୟଟି ସେହି ବ୍ୟକ୍ତିମାନଙ୍କ ପାଇଁ ଗୁରୁତ୍ୱପୂର୍ଣ୍ଣ ଯେଉଁମାନେ ‘ନିଓକ୍ଲାଉଡ୍’ ଆର୍ଥିକ ମଡେଲକୁ ବିଶ୍ଳେଷଣ କରୁଛନ୍ତି। ବିଦ୍ୟୁତ୍ ଶକ୍ତି, ନିର୍ମା ମାଇକ୍ରୋସଫ୍ଟ ରିପୋର୍ଟ ଅନୁଯାୟୀ ସମୟସୀମା ହରାଇଥିବା ଅଂଶୀଦାରମାନଙ୍କୁ ଯାଞ୍ଚ କରୁଛି।
ତୃତୀୟ ତ୍ରୈମାସିକ ରାଜସ୍ୱର ଏକ ବଡ଼ ଅଂଶ ଏକକାଳୀନ ଦେୟ ଥିଲା, ତେଣୁ ଅଭିବୃଦ୍ଧି ମୂଳ ଧାରା ଅପେକ୍ଷା ଅଧିକ ଶକ୍ତିଶାଳୀ ଦେଖାଯାଇପାରେ।
40 ବିଲିୟନରୁ 45 ବିଲିୟନ ଡଲାର ଖର୍ଚ୍ଚ ଆବଶ୍ୟକତା 7.4 ବିଲିୟନ ଡଲାରର ବର୍ତ୍ତମାନର ନଗଦ।
ଏହି ଲେଖାଟି ବିଶ୍ଳେଷଣ, ନିବେଶ ପରାମର୍ଶ ନୁହେଁ, ଏବଂ ପାଠକମାନେ ନିଷ୍ପତ୍ତି ନେବା ପୂର୍ବରୁ ପ୍ରାଥମିକ ଫାଇଲିଂ ଏବଂ ଲାଇସେନ୍ସପ୍ରାପ୍ତ ପରାମର୍ଶଦାତାଙ୍କ ସହିତ ପରାମର୍ଶ କରିବା ଉଚିତ।
ପରବର୍ତ୍ତୀ କ’ଣ ଦେଖିବା ଉଚିତ
ଯଦି ଆପଣ ନିଓକ୍ଲାଉଡ୍ ଫାଇନାନ୍ସିଂ ସ୍ଥିର ଅଛି କି ନାହିଁ ଟ୍ରାକ୍ କରୁଛନ୍ତି, ତେବେ ଏହି ସୂଚକଗୁଡ଼ିକ ସବୁଠାରୁ ଗୁରୁତ୍ୱପୂର୍ଣ୍ଣ:
ଭିନେଲ୍ୟାଣ୍ଡ ବିତରଣ ମାଇଲଖୁଣ୍ଟ: ପ୍ରଥମ କିସ୍ତି ବର୍ଷ ଶେଷ ସୁଦ୍ଧା ଆସିବ କି ନାହିଁ ଏବଂ ବାକି 2027 କ୍ବାର୍ଟର 2 ରେ।
ମାଇକ୍ରୋସଫ୍ଟର ସାର୍ବଜନୀନ ସ୍ଥିତି: ବିଳମ୍ବ କ୍ଷମତା ସହିତ ଜଡିତ କୌଣସି ନିଶ୍ଚିତକରଣ, ସଂଶୋଧନ, କିମ୍ବା ସମାପନ ନୋଟିସ୍।
ଅର୍ଥ ନିର୍ଣ୍ଣୟ ବନ୍ଦ: ମାଇକ୍ରୋସଫ୍ଟ ଏବଂ ମେଟା ଚୁକ୍ତିନାମା ବିରୁଦ୍ଧରେ ସମ୍ପତ୍ତି-ସମର୍ଥିତ ଋଣ ଆଶାକରାଯାଇଥିବା ସର୍ତ୍ତାବଳୀରେ ବନ୍ଦ ହୁଏ କି ନାହିଁ।
ସ୍ୱୟଂ-ନିର୍ମିତ ସାଇଟ୍ ପ୍ରଗତି: ନେବିୟସ୍-ନିୟନ୍ତ୍ରିତ ଡାଟା କେନ୍ଦ୍ରଗୁଡ଼ିକ ପ୍ରକୃତରେ ସମୟସୀମାରେ ପ୍ରଦାନ କରନ୍ତି କି ନାହିଁ।
ସହକର୍ମୀ ସଙ୍କେତ: Nscale, IREN, ଏବଂ CoreWeave କିପରି ସମାନ ପରିଚାଳନା କରନ୍ତି ବିଳମ୍ବ ଏବଂ ପାଣ୍ଠିର ଆବଶ୍ୟକତା।
ସାଧାରଣତଃ ପଚରାଯାଉଥିବା ପ୍ରଶ୍ନଗୁଡ଼ିକ
୨୦૨୭ ମସିହାରେ ନେବିୟସ୍ (Nebius) କେତେ ଟଙ୍କା ଖର୍ଚ୍ଚ କରିବାକୁ ଯୋଜନା କରୁଛି?
୨୦୨୬ ମସିହାର ତୃତୀୟ ତ୍ରୈମାସିକ ଆୟ ସମ୍ବନ୍ଧୀୟ ଆଲୋଚନା (earnings call) ଅନୁଯାୟୀ, ନେବିୟସ୍ ୨୦୨୭ ମସିହାରେ ପୁଞ୍ଜିଗତ ବ୍ୟୟ (capital expenditures) ବାବଦକୁ ୪୦ ବିଲିୟନ ଡଲାରରୁ ୪୫ ବିଲିୟନ ଡଲାର ଖର୍ଚ୍ଚ କରିବାକୁ ଯୋଜନା କରୁଛି।
ନେବିୟସ୍ ୨୦୨୭ ମସିହାର ଏହି ଖର୍ଚ୍ଚ ପାଇଁ ପାଣ୍ଠି କେଉଁଠାରୁ ଯୋଗାଡ଼ କରିବ?
ନେବିୟସ୍ ଆଶା କରୁଛି ଯେ ଗ୍ରାହକଙ୍କ ପକ୍ଷରୁ ମିଳୁଥିବା ଅଗ୍ରୀମ ଦେୟ (prepayments) ଏବଂ ସମ୍ପତ୍ତି-ଆଧାରିତ ଆର୍ଥିକ ସହାୟତା (asset-backed financing) ମାଧ୍ୟମରେ ଯୋଜନାର ୮୫% ପର୍ଯ୍ୟନ୍ତ ଖର୍ଚ୍ଚ ଭରଣା ହୋଇପାରିବ। ଏହା ବ୍ୟତୀତ, ଅତିରିକ୍ତ ସହାୟତା ଭାବରେ କମ୍ପାନୀ ପାଖରେ ୭.୪ ବିଲିୟନ ଡଲାରର ନଗଦ ଅର୍ଥ ମଧ୍ୟ ରହିଛି।
‘ନିଓକ୍ଲାଉଡ୍’ (neocloud) କ୍ଷେତ୍ରରେ ବିଳମ୍ବ କାହିଁକି ଏତେ ଗୁରୁତ୍ୱପୂର୍ଣ୍ଣ ବିଷୟ?
ବିଳମ୍ବ ହେଲେ ଆୟ (revenue) ଆସିବାରେ ବିଳମ୍ବ ଘଟେ, କିନ୍ତୁ ଖର୍ଚ୍ଚ ଜାରି ରହେ। ଏହା ବ୍ୟତୀତ, ଗ୍ରାହକଙ୍କ ସହ ହୋଇଥିବା ଚୁକ୍ତିନାମା ଅନୁଯାୟୀ ଏଥିପାଇଁ ଜୋରିମାନା ଦେବାକୁ ପଡ଼ିପାରେ କିମ୍ବା ଚୁକ୍ତି ବାତିଲ ହେବାର ସମ୍ଭାବନା ମଧ୍ୟ ରହିଥାଏ; ଯେପରିକି ମାଇକ୍ରୋସଫ୍ଟ (Microsoft) ସହ ନେବିୟସ୍ର ଚୁକ୍ତିନାମାରେ ଦେଖିବାକୁ ମିଳିଛି।
ନେବିୟସ୍ କ’ଣ ଲାଭଜନକ ଅବସ୍ଥାରେ ଅଛି?
ନେବିୟସ୍ କହିଛି ଯେ ୨୦୨୭ ମସିହାର ଚତୁର୍ଥ ତ୍ରୈମାସିକ ସୁଦ୍ଧା ଏହା ‘ବ୍ରେକ୍-ଇଭେନ୍’ (ଅର୍ଥାତ୍ ଲାଭ କିମ୍ବା କ୍ଷତି ନଥିବା ସ୍ଥିତି) ରେ ପହଞ୍ଚିବ ବୋଲି ଆଶା କରୁଛି (କର-ପୂର୍ବ ଆକଳନ ଅନୁଯାୟୀ)। ବର୍ତ୍ତମାନ ଏହା ସେହି ସ୍ଥିତିରେ ପହଞ୍ଚି ନାହିଁ ଏବଂ ତୃତୀୟ ତ୍ରୈମାସିକର ଆୟରେ ଏକ ଥର ମାତ୍ର ମିଳିଥିବା (one-time) ଦେୟ ଅନ୍ତର୍ଭୁକ୍ତ ଥିଲା।
‘ନିଓକ୍ଲାଉଡ୍’ (neocloud) ଏବଂ ‘ହାଇପରସ୍କେଲର୍’ (hyperscaler) ମଧ୍ୟରେ ପାର୍ଥକ୍ୟ କ’ଣ?
‘ନିଓକ୍ଲାଉଡ୍’ ମୁଖ୍ୟତଃ କୃତ୍ରିମ ବୁଦ୍ଧିମତ୍ତା ବା AI ପାଇଁ GPU କ୍ଷମତା (GPU capacity) ଭଡ଼ାରେ ଦେବା ଉପରେ ଧ୍ୟାନ କେନ୍ଦ୍ରିତ କରେ।